By the KRL Power C&I Storage Engineering & Project Finance Team · Last reviewed: October 2026
"Spend R10 million on solar and storage, and SARS hands back R3.375 million in year one."
For two years, that sentence opened almost every commercial solar pitch in South Africa. It was true — under Section 12BA, a business that brought new renewable energy assets into use could deduct 125% of the cost in the first year. At the 27% corporate income tax rate, that's a cash tax saving equal to 33.75% of the investment.
Here's what many of those pitches leave out in 2026: Section 12BA expired on 28 February 2025. It was not renewed in the 2025 Budget, and the 2026 Budget did not bring it back.
That leaves CFOs with two very different questions:
- If you're buying now: what does the permanent Section 12B allowance give you on a solar-plus-storage project — and will the battery portion survive scrutiny?
- If you already claimed 12BA: is your file ready for a SARS verification or audit, which can still arrive years after the return was filed?
We build and deliver commercial battery energy storage systems (BESS) for South African sites, and we see both questions on every finance committee agenda. This guide gives you the numbers, the tripwires and the paperwork. Use it as a working document alongside your registered tax practitioner — not instead of one.
Key takeaways
- Section 12BA (125%) applied only to qualifying assets brought into use between 1 March 2023 and 28 February 2025. Anything commissioned after that date falls under Section 12B.
- Section 12B is permanent: 100% in year one for solar PV systems up to 1 MW, and 50/30/20 over three years for larger PV and other qualifying renewable sources.
- Batteries are not a renewable energy source. They can qualify only as an integral part of a qualifying generation system. A standalone, grid-charged battery doesn't qualify.
- A rejected claim costs more than the lost deduction. You'll owe the tax, plus interest, plus an understatement penalty that starts at 25% for "reasonable care not taken" and goes far higher.
- The evidence decides the claim. System design, provenance, commissioning and invoicing records determine whether a deduction holds up.
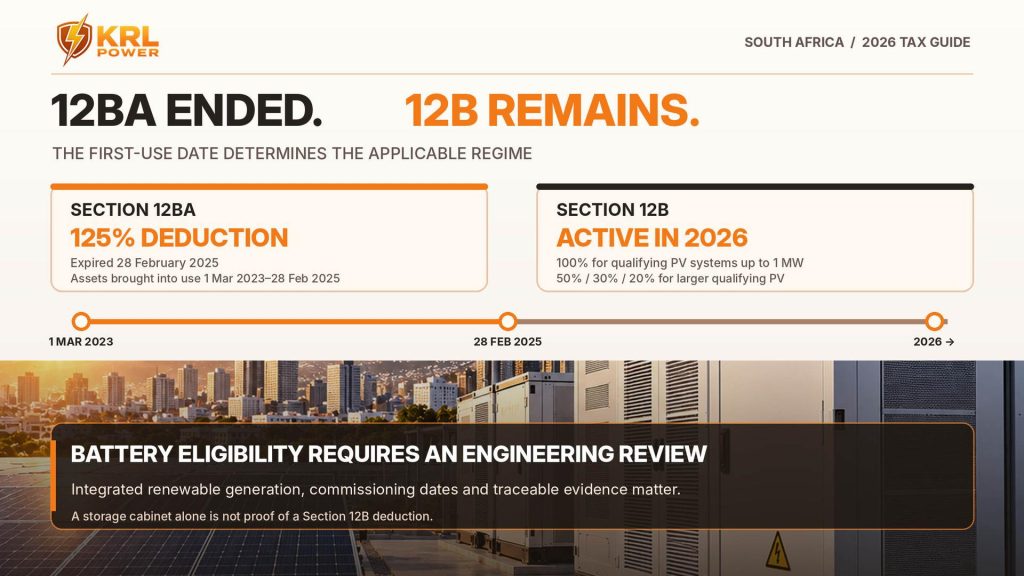
1. Section 12BA vs Section 12B: What Actually Applies to Your Project?
Before anyone builds a cash-flow model, settle one fact: the date the system was brought into use. It decides which section applies, and you can't fix it after the fact.
| Section 12BA (enhanced, temporary) | Section 12B (permanent) | |
|---|---|---|
| Status in 2026 | Expired. Covered assets brought into use 1 Mar 2023 – 28 Feb 2025 | Active |
| Deduction rate | 125% in year one | 100% in year one for PV systems up to 1 MW. 50% / 30% / 20% over three years for PV above 1 MW, wind, hydro (≤30 MW) and biomass |
| Size threshold | None | 1 MW is the line between the 100% and 50/30/20 treatment for solar PV |
| Asset condition | Explicitly new and unused | Owned by the taxpayer and brought into use for the first time in its trade |
| Batteries | Only as part of a qualifying renewable generation system | Same: only as an integral part of a qualifying generation system |
| Where it matters now | Audit defence on returns already filed | All new projects |
What this means in practice:
- A project commissioned in March 2025 or later can't claim 125%, whenever it was ordered or paid for. If a supplier still quotes you "125%" for a new installation, take that as a warning about the rest of the proposal.
- SARS can still review a 12BA claim you've already made. SARS can generally raise an additional assessment within three years of the original assessment. If there was misrepresentation or non-disclosure, that limit doesn't apply. So a 12BA deduction claimed for a 2024 or early-2025 year of assessment is very much open in 2026 and 2027.
2. The CFO's Arithmetic: What the Deduction Is Really Worth
Let's use one illustrative project throughout: R10,000,000 all-in for a hybrid system of roughly 750 kWp rooftop PV, inverters/PCS and about 1 MWh of commercial battery storage (for example, four KRL 125 kW / 261 kWh cabinets). It includes mounting, cabling, installation and commissioning. The company pays tax at 27%.
2.1 The cash tax shield under each regime
| Scenario | Deduction in Year 1 | Year 1 cash tax saving | Years 2–3 |
|---|---|---|---|
| Section 12BA (commissioned before 1 Mar 2025) | R12,500,000 (125%) | R3,375,000 (33.75% of cost) | — |
| Section 12B, PV up to 1 MW (our example today) | R10,000,000 (100%) | R2,700,000 (27% of cost) | — |
| Section 12B, PV above 1 MW | R5,000,000 (50%) | R1,350,000 | R810,000 in Y2, R540,000 in Y3 |
| Battery fails the "integral part" test | Battery portion falls back to ordinary wear-and-tear allowances | Materially lower and spread over several years | — |
Two points CFOs often get wrong:
- Section 12B is mostly a timing benefit. Over the asset's life you would claim most of this cost anyway through normal capital allowances. What the incentive buys you is the cash now. In a high-interest-rate environment, that's worth a great deal. Model it as a net present value gain, not as "free money".
- The battery is often 30–45% of the capex. If SARS treats it as a standalone asset, you lose the deduction on a large share of the project. Section 3 explains how that happens.
2.2 Operating savings: a payback you can defend to your board
You'll see slides promising a "sub-two-year payback". Treat them with care. Your finance committee, your bank's credit team and your auditors will all stress-test the model. A model that only works on the best-case assumptions will damage your credibility, and your supplier's.
A defensible model for our R10 million example uses these assumptions:
| Value driver | Illustrative assumption | Annual value |
|---|---|---|
| PV self-consumption | ~1.15 GWh/yr at a blended commercial tariff of ~R2.30/kWh | ~R2.6m |
| Battery peak-shifting and demand charge reduction | ~0.9 MWh usable, ~300 cycles/yr, peak–off-peak spread on time-of-use tariffs | ~R0.4–0.6m |
| Avoided diesel and downtime | Highly site-specific. Load-shedding has eased since 2024, so don’t build the case on it | R0 – R0.5m+ |
| Pre-tax annual benefit | ~R3.0–3.7m |
Remember that electricity savings increase taxable profit. On an after-tax basis, your annual benefit is roughly 73% of the figures above.
Result: after the year-one Section 12B shield of R2.7m, your net cash at risk falls to ~R7.3m. That gives an after-tax payback of roughly 2.7 to 3.5 years, depending on tariff structure, load profile and diesel exposure. Tariff increases make the case stronger every year: NERSA approved a double-digit Eskom increase for 2025/26 and further increases after that.
That's an excellent return for a 15-year asset. It's also a number you can defend, which matters more than a headline that falls apart under review.
3. The Three Tripwires: Why SARS Disallows Battery Storage Claims
Over the 12BA period, the same three weaknesses came up again and again in rejected or challenged claims. None of them depend on how good the battery is. They depend on design and documentation.
Tripwire 1: The "standalone BESS" trap
Sections 12B and 12BA reward assets used in the generation of electricity from specified renewable sources. A battery doesn't generate anything. SARS and National Treasury accept storage only where it forms an integral part of a qualifying generation system.
What fails:
- A battery bank installed purely as load-shedding backup, charging from Eskom or the municipal grid.
- A "retrofit" battery added later to a site, with no functional link to an on-site PV plant.
- A storage system far larger than the PV can ever charge. That sizing only makes sense as grid arbitrage, and it invites questions.
What holds up:
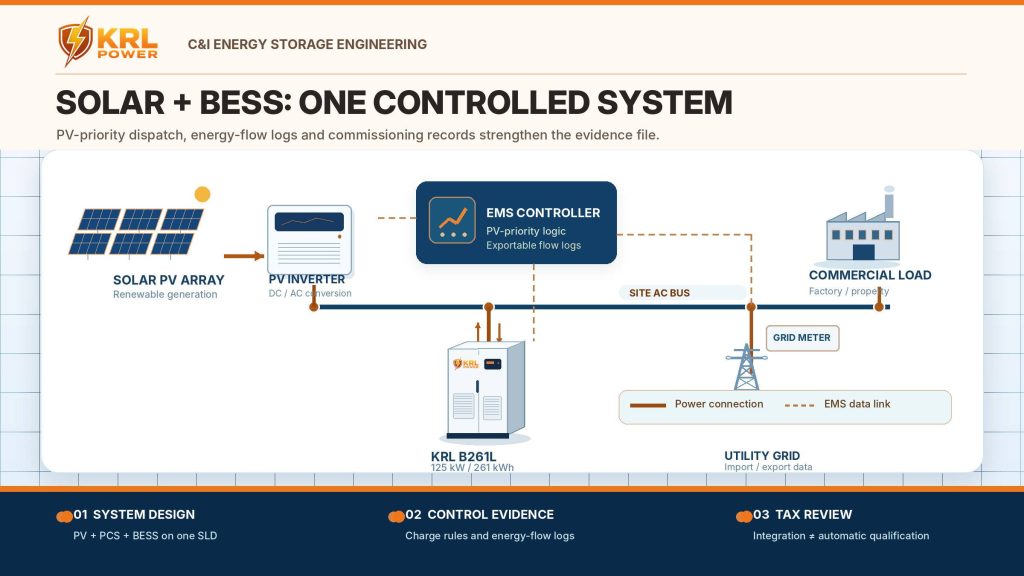
- A hybrid architecture, DC-coupled or a controlled AC-coupled design, where the battery's main job is to capture and shift on-site solar generation.
- An energy management system (EMS) set to give PV charging priority. Any grid-charging rules should be deliberate and documented. Agree your grid-charging policy with your tax practitioner before commissioning.
- Energy-flow records showing how much of the battery's charge came from on-site PV over time.
- Quotes, contracts and invoices that present the storage as one component of a single solar-plus-storage system, not a separate backup purchase.
Tripwire 2: Provenance — "new and unused", and proving it
For 12BA claims, the law required assets to be new and unused. Under Section 12B, the asset must be owned by the taxpayer and brought into use for the first time in its trade. SARS also tests cost: the deduction is limited to the actual cost or the arm's-length cash price, whichever is lower.
In both cases, your file must be able to answer three questions: What exactly did we buy? From whom? At what genuine cost?
That's where cheap, locally assembled cabinets become a tax problem rather than just an engineering one. The South African market contains packs built from:
- Second-life or "B-grade" cells pulled from other applications.
- Cells with no traceable batch records back to the cell manufacturer.
- Imports with customs and invoicing records that don't match the equipment on site.
If your supplier can't connect the serial numbers on site to factory test records, cell batch data and clearance documents, you can't show SARS what you own. You also can't show your insurer.
Tripwire 3: "Brought into use" means energised, commissioned and documented
Equipment sitting in a warehouse on 28 February, or at your financial year-end, hasn't been brought into use. SARS will look for evidence that the system was installed, energised, commissioned and actually operating in your trade. That means:
- A signed commissioning / site acceptance report with a date.
- An electrical Certificate of Compliance (CoC).
- Registration or authorisation of the embedded generator with your municipality or Eskom, where required.
- First operating data from the EMS or monitoring platform.
Long site works, delayed electrical sign-off and grid authorisation backlogs can push the "brought into use" date into the next tax year. On a 12BA project, the same delay could cost the 125% altogether.
What a failed claim actually costs
If SARS disallows the deduction, you repay the tax, plus interest, plus an understatement penalty under the Tax Administration Act. The rate depends on behaviour:
| SARS finding | Standard case |
|---|---|
| Reasonable care not taken in completing the return | 25% |
| No reasonable grounds for the tax position taken | 50% |
| Gross negligence | 100% |
| Intentional tax evasion | 150% (up to 200% for repeat or obstructive cases) |
For most businesses that claimed in good faith, a disallowed battery deduction falls in the first two rows. On a R3m battery portion, that's R810,000 of tax, plus R200,000 to R400,000 in penalties, plus interest. Your defence is a well-documented position and a written opinion from your tax practitioner, made before filing.
4. The Five-Document Audit Dossier: What SARS, Your Bank and Your Insurer Will Ask For
Three parties will look at your project: SARS, the green finance desk at your bank (Standard Bank, Absa, Nedbank, FNB and others), and your commercial property insurer. They ask overlapping questions. Build one dossier that answers all three.
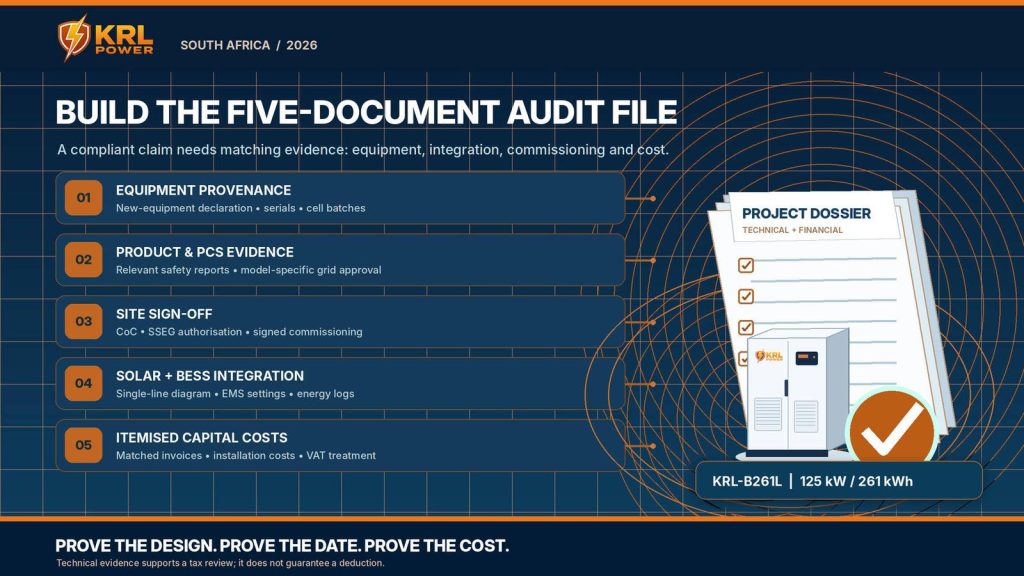
Document 1: Provenance and "new equipment" declaration
- Manufacturer's declaration that the equipment is new and unused, listing serial numbers.
- Cell-level traceability: cell manufacturer, batch/lot data, and pack and cabinet factory test records.
- Commercial invoice, packing list, bill of lading and customs clearance documents that match the serial numbers installed on site.
Document 2: Product certification
- IEC 62619: safety requirements for industrial lithium batteries.
- UL 9540A test report: the thermal runaway fire propagation test method insurers and fire engineers increasingly ask for in commercial buildings.
- IEC 62477-1 / IEC 62109 (as applicable) for the power conversion equipment.
- NRS 097-2-1: South Africa's grid-interconnection requirements for embedded generation. This applies to the grid-tied inverter/PCS. Make sure the specific model installed is on the approved list of your municipality or Eskom.
- UN 38.3: transport safety for the lithium battery modules.
Document 3: Installation compliance and grid authorisation
- Certificate of Compliance (CoC) under SANS 10142-1, issued by a registered electrical contractor. Include embedded-generation requirements (SANS 10142-1-2) where applicable.
- Small-scale embedded generation (SSEG) registration or approval from your municipality or Eskom.
- Commissioning and site acceptance report, dated and signed. This document establishes your "brought into use" date.
Document 4: Integration evidence
- Single-line diagram (SLD) showing the PV array, inverters/PCS, battery and point of connection as one system.
- EMS control philosophy: how the system prioritises PV charging, and when (if ever) it charges from the grid.
- Exportable energy-flow reports: PV generation, PV-to-battery charging, battery discharge and grid import. Keep these for at least five years.
Document 5: The CAPEX invoice split
How costs appear on invoices largely decides how cleanly they can be claimed. Agree the structure with your EPC and tax practitioner before the purchase order goes out.
| Cost line | Typical treatment (confirm with your practitioner) |
|---|---|
| PV modules, inverters/PCS, battery cabinets, EMS hardware | Core qualifying assets |
| Mounting structures, DC/AC cabling, switchgear dedicated to the system | Generally form part of the qualifying system cost |
| Direct installation, erection and commissioning labour | Generally included as direct cost of installation |
| Civil works and foundations dedicated to the system | Needs case-by-case analysis. Itemise separately |
| General building upgrades, roof repairs, unrelated electrical work | Usually not part of the qualifying asset |
| Interest and finance charges | Not part of the asset cost. Deal with them separately |
| Input VAT (for VAT vendors) | Excluded from the cost base where you can claim it back |
| Extended warranties and O&M contracts | Usually treated as operating expenditure, not capex |
One more thing to keep in mind: if you later sell or dispose of the assets, the allowances you've claimed can be recouped and taxed. Build that into your exit or refinancing plans.
5. Already Claimed 12BA? A 15-Minute Audit-Readiness Check
If your company claimed the 125% deduction on a solar-plus-storage project, check your file against these questions now:
- Is there a dated commissioning report showing the system operating on or before 28 February 2025 (or within the year of assessment claimed)?
- Is there a CoC and, where required, grid or municipal authorisation with dates that fit the claim?
- Can you match every battery serial number on site to manufacturer, customs and invoice records?
- Do you have a manufacturer's new-and-unused declaration?
- Does the SLD and EMS configuration show the battery working as part of the PV system?
- Can you export historical energy-flow data showing PV-sourced charging?
- Are non-qualifying costs (finance, general building works, O&M) excluded from the deduction?
- Do you have a written technical position from your tax practitioner on the battery's inclusion?
If you answered "no" to two or more, get your tax practitioner involved now. Gaps found and fixed before SARS asks are treated very differently from gaps SARS finds first. Under the penalty table, a voluntary disclosure made before an audit notice can cut the penalty sharply, in many cases to zero.
6. Where KRL Power Fits: Hardware That Comes With Its Own Evidence
Most suppliers sell you a cabinet. Assembling the proof is left to you, months later, when a SARS letter or a bank covenant review arrives. We take the opposite approach: the documentation is designed and delivered with the hardware.
A Tax & Finance Compliance Pack with every system. KRL C&I storage systems, from the 125 kW / 261 kWh cabinet up to multi-MWh projects, ship with a project dossier that includes:
- Factory declaration of new equipment with serial-number mapping.
- Cell-to-cabinet traceability records.
- Certification reports for the delivered configuration.
- Reference hybrid single-line diagrams for your EPC and electrical contractor.
It's structured around the five-document dossier above, so your tax practitioner, lender and insurer all work from the same file.
Factory-direct provenance. We control the chain from qualified cell supply through pack and cabinet integration to factory acceptance testing. That's why we can link the serial number on your site to its production records. Assembled-in-a-yard cabinets usually can't.
Solar-first by design. KRL systems are built for hybrid PV-plus-storage operation. The integrated controller coordinates PV, storage, grid and, where needed, diesel, with configurable PV-priority charging. It produces exportable energy-flow reports your tax practitioner can attach to the file.
Prefabricated for fast commissioning. Pre-integrated, factory-tested cabinets cut on-site integration work. That shortens the time from delivery to a signed commissioning report, which protects your "brought into use" date when a financial year-end is close.
A note on responsibility: No equipment supplier can guarantee a tax outcome, and you should be wary of any that claims to. Your tax practitioner decides how the deduction is claimed, and SARS decides whether it's allowed. What we guarantee is that the engineering and provenance evidence your practitioner needs exists, matches what's installed, and arrives on time.
Don't Let Missing Paperwork Cost You the Deduction
The 125% era is over. Section 12B still delivers a powerful year-one cash shield, and electricity tariffs keep rising. For South African businesses, a well-designed solar-plus-storage system remains one of the best-returning capital projects available.
A cheaper cabinet can easily cost you more if it loses you the deduction. The deduction only holds if the design, the provenance and the paperwork support it.
The project review covers your load profile, PV-coupled KRL storage sizing and the technical evidence your tax practitioner will need.
Disclaimer: This article is general information based on the Income Tax Act and Tax Administration Act as publicly understood at the date of review (October 2026). It isn't tax, legal or financial advice. Tax outcomes depend on your specific facts. Consult a registered tax practitioner before claiming any deduction. Figures are illustrative.
About the authors: The KRL Power C&I Storage Engineering & Project Finance Team designs and delivers commercial and industrial battery energy storage systems for markets including South Africa, working alongside local EPCs, electrical contractors and tax advisers on hybrid PV-plus-storage projects.